Calculate from your production baseline
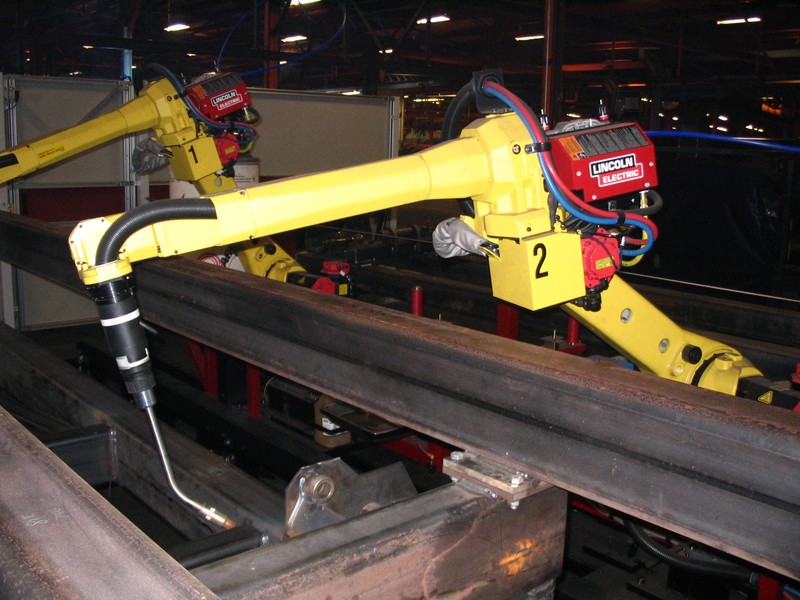
Welding robot return on investment depends on the work allocated to the system and the costs it actually changes. Start with measured production records, then compare the current method with a defined proposed configuration. A robot price alone cannot establish payback.
Record loading, welding, unloading, inspection, rework and changeover separately. Use accepted parts as the output measure. A faster welding segment has limited financial value if another operation constrains finished output or demand cannot absorb additional production.
Include the whole investment
- Equipment: arm, controller, welding package and integration.
- Application: fixtures, process trials, programming and acceptance work.
- Site: utilities, safeguarding, extraction and installation.
- Ownership: consumables, maintenance, training, downtime and financing.
- Commercial scope: transport, taxes and any separately quoted work.
Separate expenses already incurred from incremental project costs. Count redeployed labor as cash savings only when it reduces actual spending; otherwise describe the operational benefit separately. Avoid counting the same production improvement under both labor and throughput.
Use transparent formulas
Annual net benefit = verified annual cost savings + contribution from additional saleable output − additional annual operating costs.
Simple payback in years = total initial investment / annual net benefit, only when annual net benefit is positive. A nonpositive result provides no finite simple payback.
These are planning calculations, not promised returns. Simple payback excludes the time value of money. Compare conservative and expected cases, including lower utilization, more changeovers and delayed ramp-up. Keep each assumption tied to a production record, trial result or written quote.
Prepare a review
Share part drawings, batch sizes, current process times and acceptance criteria with CBOXTEC to discuss the proposed equipment scope. Confirm quote inclusions before treating an estimate as an investment budget.